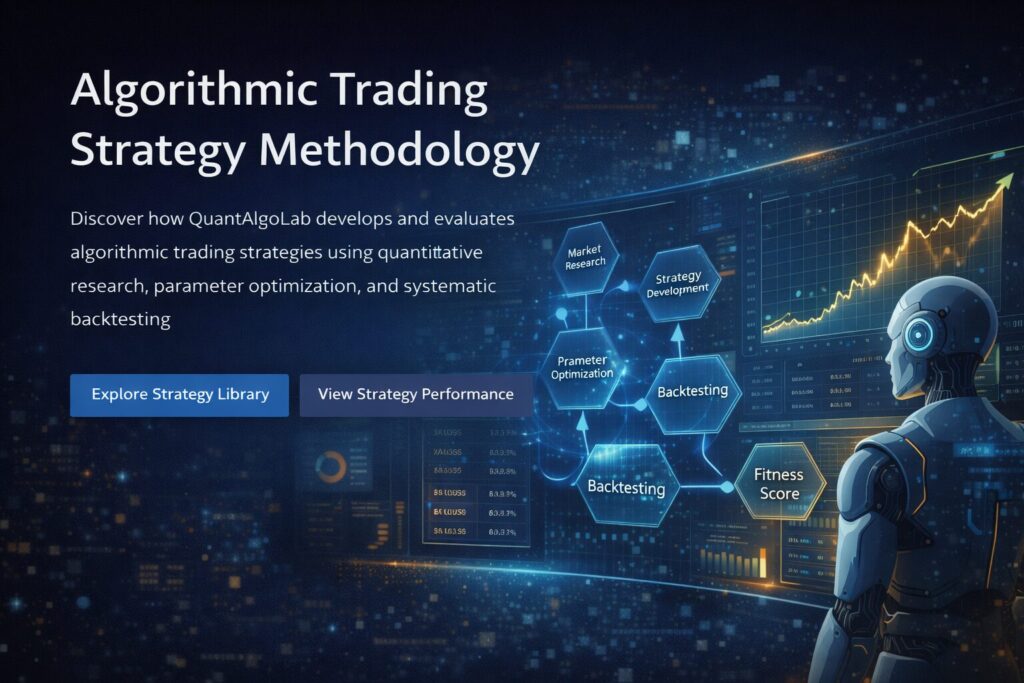
Algorithmic trading strategy methodology explains how quantitative trading systems are developed, optimized, and evaluated using systematic research and backtesting.
At QuantAlgoLab, algorithmic trading strategies are developed through a structured quantitative research process. Instead of relying on subjective market opinions, each strategy is created using data-driven analysis, systematic hypothesis testing, and statistical evaluation.
This research-driven approach helps identify trading models that demonstrate stable behavior across historical market conditions while maintaining controlled risk exposure.
Strategies are built using historical market data analysis and statistical research rather than discretionary trading decisions.
Each trading model follows predefined algorithmic rules to ensure consistent and repeatable trade execution.
Risk control and drawdown management are incorporated into the strategy development process from the beginning.
Every trading robot at QuantAlgoLab follows a structured quantitative research process designed to identify robust trading strategies through systematic analysis and optimization.
The development process begins with identifying a market behavior hypothesis, such as trend persistence, volatility breakout, or mean reversion patterns.
Trading rules are defined based on technical indicators, market structure, or statistical relationships to transform the hypothesis into a systematic algorithm.
Strategy parameters are optimized across multiple combinations to identify robust configurations with favorable risk-return characteristics.
Each strategy undergoes extensive historical testing to evaluate drawdown, trade consistency, and long-term performance potential.
This structured algorithmic trading strategy methodology ensures that every strategy developed by QuantAlgoLab undergoes rigorous research, optimization, and performance evaluation.
Beyond traditional backtesting, QuantAlgoLab evaluates the robustness of algorithmic trading strategies using multiple validation techniques. These tests help determine whether a strategy maintains stable performance under different market conditions and parameter variations.
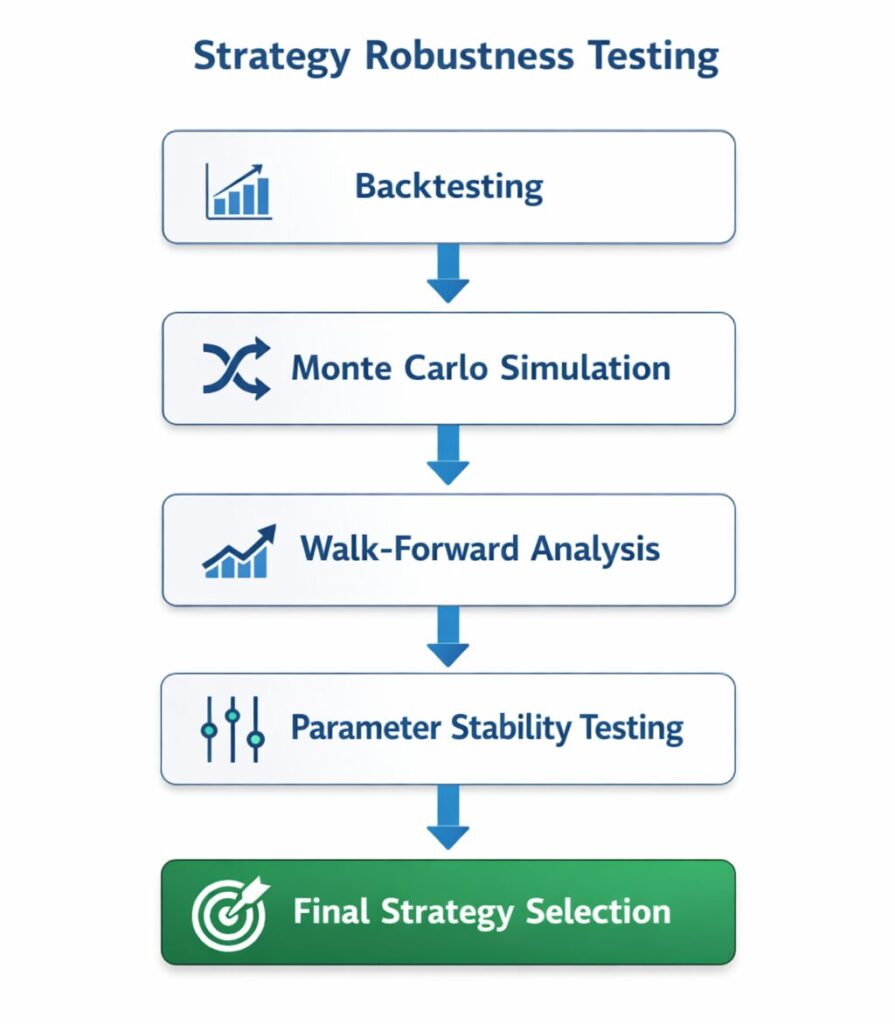
Monte Carlo simulations randomize trade sequences and execution conditions to evaluate how a strategy may perform under different market scenarios and execution variability.
Walk-forward testing repeatedly re-optimizes strategy parameters across different historical periods to evaluate how well a trading system adapts to evolving market conditions.
Parameter stability analysis evaluates how sensitive a strategy’s performance is to parameter changes, helping identify robust parameter ranges rather than single optimized values.
Robustness testing plays a critical role in algorithmic trading strategy development by ensuring that optimized strategies maintain consistent behavior across different datasets and market environments.
Once a trading strategy is developed, its parameters are optimized through systematic testing across multiple parameter combinations.
This optimization process helps identify configurations that demonstrate consistent behavior while avoiding overfitting to historical data.
To compare different strategies objectively, QuantAlgoLab applies a fitness score evaluation framework that considers multiple performance factors including risk-adjusted return, drawdown stability, and trade distribution.
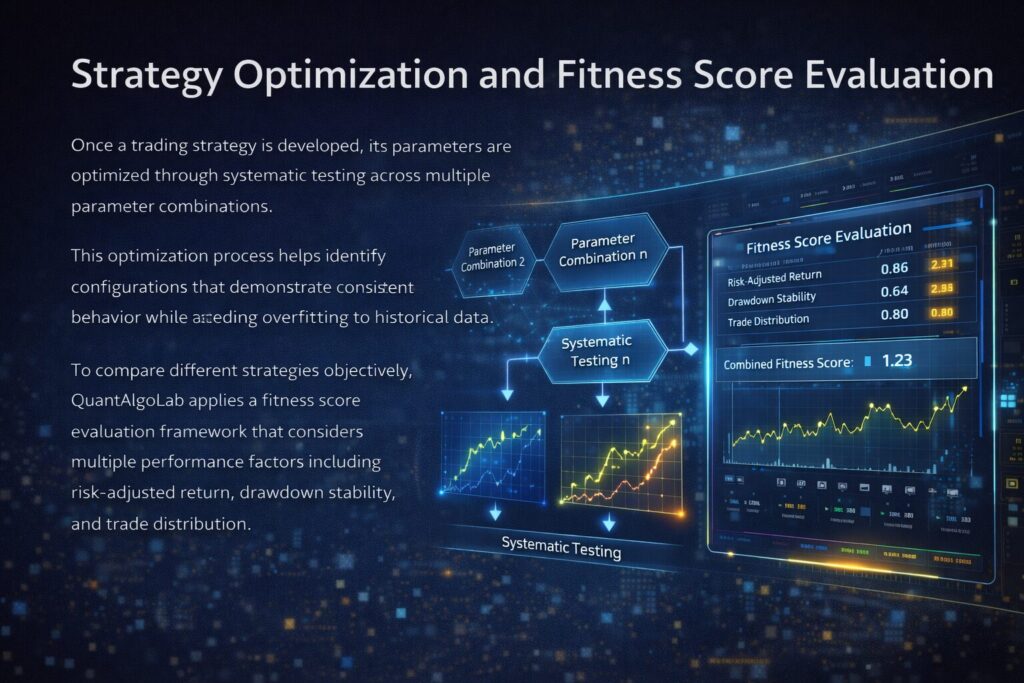
Each algorithmic trading strategy is evaluated using multiple performance metrics to assess stability, risk exposure, and consistency during historical backtesting.
Evaluates the largest peak-to-trough equity decline to measure downside risk during historical backtesting.
Analyzes the smoothness and consistency of the equity curve to identify stable strategy behavior.
Examines the frequency and distribution of trades to understand how the strategy performs across market conditions.
Measures strategy performance relative to its level of risk and drawdown exposure.
The QuantAlgoLab research pipeline illustrates the structured process used to transform trading ideas into fully tested algorithmic trading strategies.
Identify trading opportunities across gold, crypto, forex and index markets.
Develop quantitative trading models such as trend following and mean reversion.
Optimize parameters across assets, timeframes and market conditions.
Validate strategy behavior using multi-year historical data.
Evaluate strategies using drawdown, ROI and stability metrics.
Strategies are categorized into Foundation, Professional or Institutional tiers.
No martingale • No grid • No revenge trading
Learn more about our algorithmic trading research, strategy development process, and performance evaluation framework.
Browse the collection of algorithmic trading strategies developed using systematic research and quantitative analysis.
Understand how strategy performance is evaluated using backtesting metrics and quantitative fitness score analysis.
View available access options for QuantAlgoLab algorithmic trading strategies and research tools.
Algorithmic trading strategies are developed through a structured process that includes market research, rule-based strategy design, parameter optimization, and systematic backtesting.
Strategy optimization is the process of testing multiple parameter combinations to identify configurations that produce stable risk-adjusted performance.
Yes. Each trading strategy is optimized specifically for a particular asset and is not intended to be used across different instruments.